All Categories
Featured
Reviewing Top-Rated Medicare Advantage Policies
Table of Contents
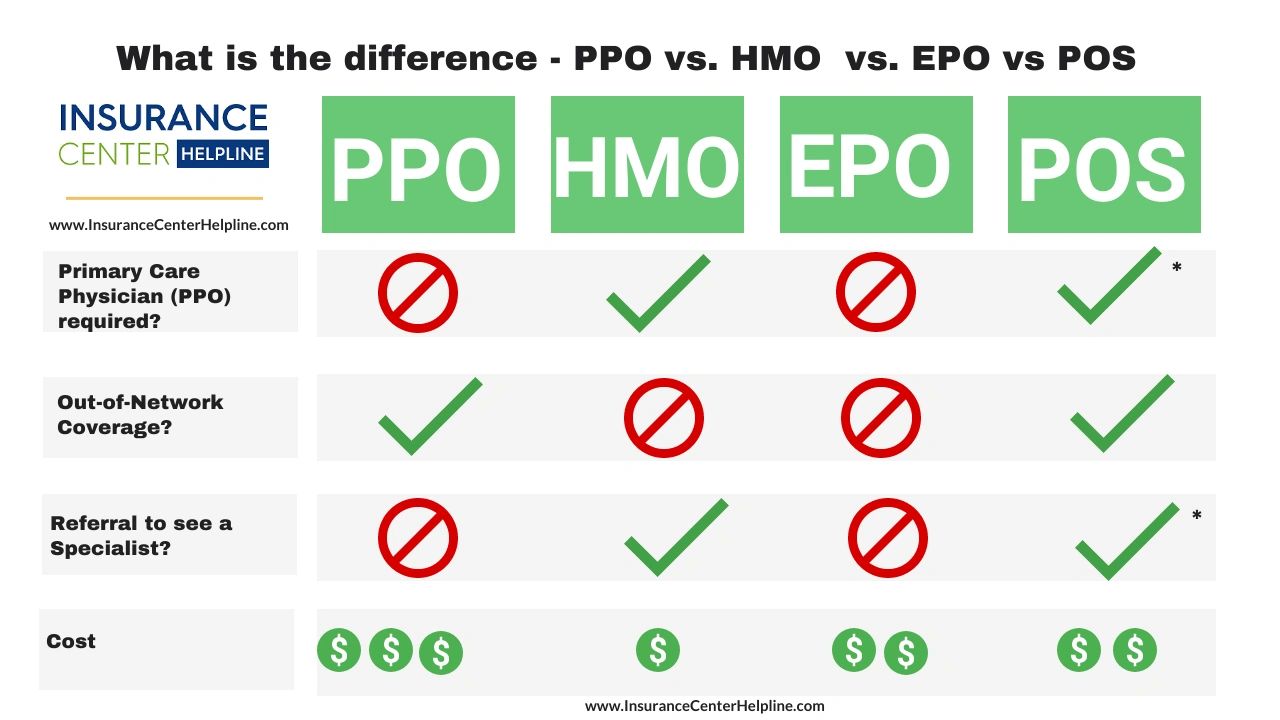
Like all health insurance, receiving in-network care is best to keep your out-of-pocket expenses low. Unlike HMO plans that won't cover any part of your bill if you seek out-of-network care (other than in a covered emergency situation), you can get out-of-network care when taking a trip out of your regular plan network location with a PPO policy.
Insurance in Tustin CACost-conscious people ought to think about a few drawbacks to PPO prepares that may make getting care more costly. While they're flexible and practical, PPO plans have higher premiums.
If you do have a deductible, it's likely to be more costly than other plan types. While your insurer will share the expense with you, you'll likely pay a greater coinsurance percentage for out-of-network suppliers. When you check out an in-network service provider, they'll submit your claim to your health insurance business in your place.
PPO policyholders might find the claim filing procedure complicated if they're not utilized to it or lengthy if they frequently require out-of-network care from a professional. In 2023, the typical annual premium for a group PPO plan was $8,906 for self-only coverage and $25,228 for family coverage2. Employers contributed $7,399 toward a self-only strategy, and workers contributed $1,507.
Reviewing Top-Rated Medicare Supplement Options
The average deductible for PPO strategies was $1,281. As pointed out above, PPO plans purchased on the ACA markets likewise have an optimum out-of-pocket limitation of $9,450 for self-only coverage and $18,900 for family plans.
Yes No Yes No Some plans do. The majority of strategies do. Whether you have an HMO or PPO strategy, you can leverage a health reimbursement arrangement (HRA) to lower out-of-pocket medical expenditures.
Insurance in Tustin CAOnly companies can release and contribute towards an HRA. Companies utilize an HRA to provide their workers a monthly allowance to spend for medical expenses. When a worker buys an eligible item or service, they send paperwork showing evidence of purchase, and their employer compensates them as much as their allowance quantity.
Maximizing IUL Growth Benefits in Retirement
Worker repayments will be tax-free if their individual health plan provides minimum necessary protection (MEC). Companies can compensate staff members for out-of-pocket expenditures and health insurance premiums, including those for an HMO or PPO plan. Specific coverage HRA (ICHRA): An ICHRA is likewise a stand-alone HRA, however it's readily available to employers of all sizes and has no contribution limits.

However, they need to have a certifying type of specific health protection to take part. Companies can set various allowances based on worker classes for added personalization. Group coverage HRA (GCHRA): Also referred to as an incorporated HRA, a GCHRA is for companies of any size who provide a group health insurance. Only employees enrolled in their company's group strategy can get involved.
While they have no maximum contribution limits, the internal revenue service does not allow repayments for regular monthly premiums. No matter whether it's utilized in coordination with an HMO or PPO strategy, there's an HRA that can assist workers spend for their out-of-pocket medical costs and, often, their health insurance premiums. An HRA is a popular alternative choice over traditional health advantages since they're economical for employers and versatile enough for every single worker.
Low-Cost Plan Choices for Veterans
An HMO may be your best choice if you're trying to find a strategy with a low premium. A PPO strategy offers additional versatility if you need more control over your health care. That's why investigating these strategies thoroughly, including their pros, cons, and average costs, is the finest initial step you can take before making a decision.
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, however it's offered to companies of all sizes and has no contribution limits.
They need to have a certifying form of private health protection to get involved. (GCHRA): Also known as an integrated HRA, a GCHRA is for companies of any size who use a group health strategy. Just employees enrolled in their employer's group strategy can participate.
Essential Part D Selection Tips in 2026
While they have no optimum contribution limitations, the IRS does not permit compensations for regular monthly premiums. No matter whether it's used in coordination with an HMO or PPO plan, there's an HRA that can help employees pay for their out-of-pocket medical expenses and, in some cases, their medical insurance premiums. An HRA is a popular alternative choice over standard health advantages since they're affordable for companies and flexible enough for each worker.
An HMO may be your best bet if you're searching for a strategy with a low premium. However, a PPO strategy offers extra versatility if you need more control over your health care. That's why investigating these plans carefully, including their pros, cons, and average costs, is the very best initial step you can take in the past deciding.

Latest Posts
Reviewing Top-Rated Medicare Advantage Policies

Reviewing 2026 Term Life Insurance Rates for Families

Optimizing Indexed Universal Life Policy Potential for Retirement